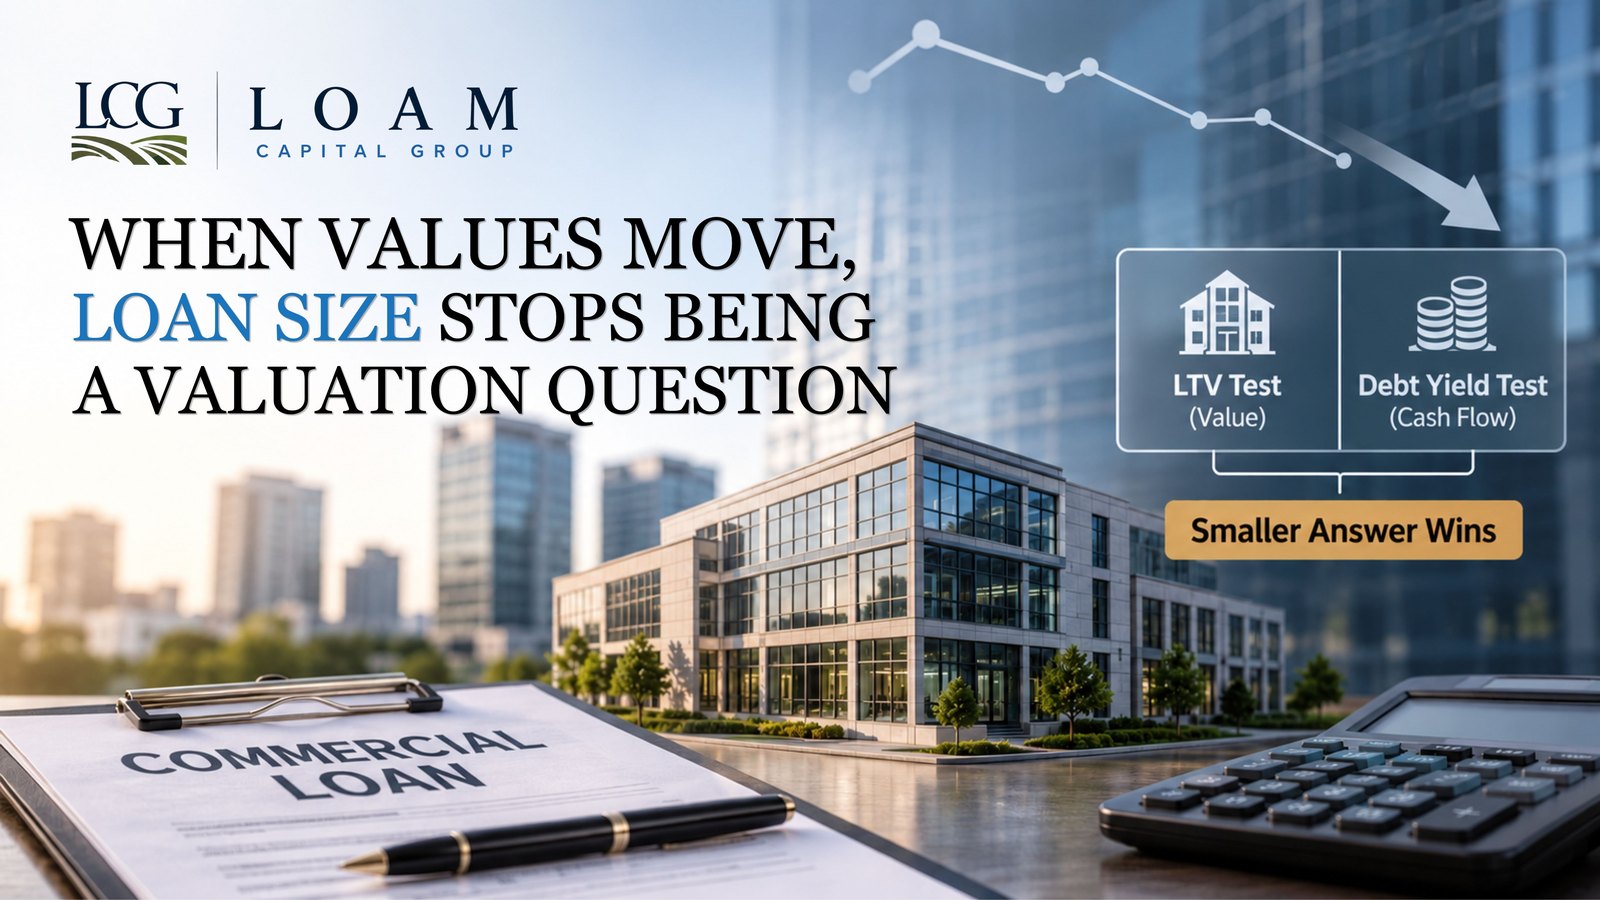
Short answer. A commercial loan is sized by two separate tests, and the smaller answer wins. The first test is a share of the property's appraised value - the loan-to-value test. The second is a cash-flow test, which asks how much debt the property's net operating income can support, most often measured as a debt yield: net operating income divided by the loan amount. When appraised values are stable, the value test usually sets the loan size. When values are repricing, the appraisal becomes the least reliable number in the file, and the cash-flow test starts binding first. CBRE Research has projected cap rates rising 40 to 60 basis points while the 10-year Treasury stays near 5%, which would reduce average values. That is a forecast, not a recorded outcome, and forecasts of this kind are regularly wrong in both directions. Lenders interviewed by Commercial Observer in November 2026 described exactly this shift - running more rate and valuation scenarios, requiring debt service cushions, and accepting lower loan proceeds rather than lending against a value they do not believe will hold.
Two tests, and the smaller answer wins
Ask how a commercial lender decides how much to lend and you will usually get one answer: a percentage of value. That is only half of it.
Nearly every commercial loan is sized by running two tests and taking the lower result.
- The value test. The loan cannot exceed a set share of what the property is worth. This is the loan-to-value ratio. It depends entirely on an appraisal.
- The cash-flow test. The loan cannot exceed what the property's income can carry. A common form is the debt yield — net operating income divided by the loan amount. A lender sets a minimum, and the loan is sized down until it clears.
Net operating income is the rent and other income a property collects over a year, minus what it costs to run — taxes, insurance, maintenance, management. It does not subtract the loan payment. That is the point of it: it measures the building, not the financing.
Those two are the arithmetic of it, and they are not the whole decision. A lender also weighs things that do not reduce to a formula — the sponsor's experience and liquidity, the guaranty, lease rollover, the condition and location of the property, and its own appetite for that asset type at that moment. Any one of them can shrink a loan or stop it entirely.
The two tests answer different questions. The value test asks what someone would pay for the building. The cash-flow test asks what the building actually earns. In a calm market those answers track each other closely, and the value test is usually the one that binds. That is why loan-to-value is the number most borrowers and most investors talk about.
It is also why the conversation gets confused when values start moving.
Why the value test breaks first
An appraisal is an estimate built largely from recent comparable sales. When sales slow and the sales that do happen reprice, the inputs to that estimate get thin and stale at the same moment.
CBRE Research has projected cap rates rising at least 40 to 60 basis points while the 10-year Treasury holds near 5%, a move that would reduce average values. That is a projection and not a settled fact — the figure is a forecast of what could happen, not a measurement of what has. We looked at what that repricing means for the equity in a building in our note on cap rate spreads.
For a lender the practical problem is different and more immediate. A loan sized today against an appraisal is sized against a number that may be measuring a market that has already changed. Nothing about that is unusual in a repricing market — it is simply what appraisals do at a turn. But it means the value test stops being the conservative test. It becomes the loose one.
Net operating income does not have that problem in the same way. It is not an estimate of what a buyer would pay. It is what the property collected, minus what it cost to run. It can fall — tenants leave, expenses rise, concessions get given — but it is measured rather than inferred, and it does not move because the Treasury market moved.
That is the whole reason the second test matters more right now. A loan sized off cash flow is sized off something the market cannot reprice overnight.
This is what lenders say they are doing
Commercial Observer interviewed commercial real estate lenders in November 2026 about underwriting in a higher-for-longer rate environment. The answers were consistent, and they describe the shift above in plain terms.
Tony Fineman, head of originations at Acore Capital, said the firm “will not pursue a deal unless we are confident that it works with some level of cushion to today's interest rates,” and that it wants sponsors “investing a meaningful amount of cash subordinate to our loan.” Jason Kollander, head of real estate credit at BDT & MSD Partners, said his team is “focused on debt service ratio cushions, protecting against rate volatility through hedges.” Jai Agarwal, president and COO of Dwight Investment Management, said the firm is “running more scenario analyses to make sure every deal holds up across a wider range of rate and valuation outcomes.”
Chris Duey, a senior managing director at Principal Asset Management, named the consequence directly: “Elevated rates create challenges for borrowers through higher debt costs and lower proceeds.” Lower proceeds means a smaller loan against the same building. Steve Caldwell, who leads large loan CMBS at Wells Fargo, described the shift as going “back to basics on credit work.”
A common thread runs through those comments: each describes testing a loan against cash flow, rate scenarios or sponsor equity rather than against a higher appraised value. Five lenders are not the whole market, none of them were speaking about debt yield specifically, and each was describing his own firm's approach rather than an industry standard. The direction they describe is consistent, which is worth noting without treating it as a rule.
The arithmetic of a tighter cash-flow test
The effect is easier to see with numbers. Take a property producing $1,200,000 of net operating income. Debt yield is net operating income divided by the loan amount, so the maximum loan under a given minimum is simply the income divided by that minimum.
| Minimum debt yield required | Maximum supportable loan | Change |
|---|---|---|
| 8.0% | $15,000,000 | — |
| 9.0% | $13,333,000 | −$1,667,000 |
| 9.5% | $12,632,000 | −$2,368,000 |
Illustrative arithmetic only, using the standard definition of debt yield. Not a quote, a term sheet, or a description of any Loam Capital Group offering.
A 1.5-point move in a single underwriting standard removes more than $2.3 million of loan proceeds from a building whose income never changed and whose appraisal never changed. No rate was quoted and no value was marked down. The lender simply required more income per dollar lent.
That is the mechanism behind “lower proceeds.” It is also why a borrower can be told no by a bank that has not changed its opinion of the property at all.
Bank credit is moving the same direction
This is not a handful of lenders being cautious. The Federal Reserve's October 2026 Senior Loan Officer Opinion Survey — 79 institutions responding, including 61 domestic banks, with responses collected between September 21 and October 5, 2026 — found that banks “reported having tightened, on net, lending standards for all commercial real estate (CRE) loan categories,” naming loans secured by construction and land development, nonfarm nonresidential properties, and multifamily properties. The same survey found banks reported “weaker demand for all CRE loan categories.”
All categories, not some. Standards and demand moving together.
What to ask about this
If you own commercial property, the useful question before your next financing conversation is not what loan-to-value a lender will go to. It is what their minimum cash-flow test is, and which of the two tests limits your loan. Those are different conversations, and only one of them is still under your control through operations.
If you are evaluating a private credit manager, the question is similar and more revealing: on a typical loan, which test binds first? A manager who can answer that specifically is describing a real underwriting process. The answer also tells you something a loan-to-value figure alone does not — whether the loan was sized against an opinion of value or against collected income.
Neither test removes risk, and no amount of underwriting removes the possibility of loss. The narrower point is that in a market where values are moving, the test anchored to cash flow is doing more of the work than the one anchored to an appraisal.
We cover the structural differences between lending and owning in debt funds vs. equity funds, how commercial files are evaluated in how commercial loan applications are underwritten, and the valuation question itself in as-is value vs. ARV.
Common questions
What is debt yield in commercial real estate?
Debt yield is a property's net operating income divided by the loan amount, expressed as a percentage. It measures how much income a lender receives per dollar lent, without reference to an appraised value or an interest rate. Because it uses collected income rather than an estimate of value, lenders often rely on it more heavily when property values are moving.
How is a commercial loan amount actually determined?
Most commercial loans are sized by running at least two tests and taking the lower result. One caps the loan at a share of the property's appraised value, and one caps it at what the property's net operating income can support. Whichever produces the smaller number sets the loan. Which test binds depends on the property and on market conditions.
Why would a lender reduce loan proceeds when nothing about my property changed?
Because the lender changed its own minimum standard, not its view of your property. Raising a required debt yield reduces the supportable loan on identical income. Lenders interviewed by Commercial Observer in November 2026 described tightening underwriting to hold up across a wider range of rate and valuation outcomes, with Principal Asset Management's Chris Duey naming lower proceeds as a direct result of elevated rates.
Did banks tighten commercial real estate lending standards in 2026?
Yes. The Federal Reserve's October 2026 Senior Loan Officer Opinion Survey, with 79 responding institutions including 61 domestic banks and responses collected September 21 through October 5, 2026, reported that banks tightened lending standards on net for all commercial real estate loan categories - construction and land development, nonfarm nonresidential, and multifamily - and reported weaker demand across all of them.
Sources
- The October 2026 Senior Loan Officer Opinion Survey on Bank Lending Practices — Board of Governors of the Federal Reserve System, Oct 2026
- Commercial Real Estate Lenders Adapt to Higher-Forever Rates — Commercial Observer, Nov 3, 2026
- CBRE: Cap Rates Could Rise 40-60 bps as 10-Year Tops 5% — CRE Daily, Oct 28, 2026
This article is for information only. It is not investment, legal, or tax advice, and it is not an offer to sell or a solicitation to buy any security. Any offer is made only through official fund documents to verified accredited investors.